Table of contents
Quick answer
Ask for the denial in writing, with the policy or contract language it relies on. Federal rules require the carrier's decision to come in writing within 120 days, and you normally have at least 2 years from a written denial to sue. Answer the stated reason with evidence: timestamped photos, the bill of lading, a body shop estimate. If that fails, escalate to the broker, the carrier's insurer, an FMCSA complaint and small claims court. For a large loss, or a fight over policy wording, talk to your own insurer and a lawyer.
Why claims get denied
Denials cluster around a handful of reasons, and most are about evidence rather than fault. Knowing which one you were given tells you what you are arguing about.
| The reason given | What it means | What can answer it |
|---|---|---|
| Not noted at delivery | The delivery bill of lading was signed clean, so the carrier says the car came off the truck undamaged | Timestamped delivery photos, the driver's copy, anything sent in writing the same day |
| Pre-existing damage | The mark was recorded at pickup, or the pickup report is too vague to rule it out | Pickup photos and the pickup bill of lading, read beside the delivery ones |
| Personal items | Belongings in the car sit outside cargo cover and are often excluded outright | Rarely anything. This is the reason to ship the car empty |
| Mechanical or electrical fault | The carrier says loading, securing and transport did not cause it | A mechanic's written opinion linking the fault to how the car was handled |
| Outside the carrier's control | An act-of-God or inherent-vice argument: weather, debris, or a condition of the car itself | Evidence of how the car was secured and stored, plus the carrier's burden of proof |
| Filed late or filed wrong | The claim missed a contract deadline, or was never a proper written claim | The dates you can prove, and the federal minimums a contract cannot undercut |
Not noted at delivery
- What it means
- The delivery bill of lading was signed clean, so the carrier says the car came off the truck undamaged
- What can answer it
- Timestamped delivery photos, the driver's copy, anything sent in writing the same day
Pre-existing damage
- What it means
- The mark was recorded at pickup, or the pickup report is too vague to rule it out
- What can answer it
- Pickup photos and the pickup bill of lading, read beside the delivery ones
Personal items
- What it means
- Belongings in the car sit outside cargo cover and are often excluded outright
- What can answer it
- Rarely anything. This is the reason to ship the car empty
Mechanical or electrical fault
- What it means
- The carrier says loading, securing and transport did not cause it
- What can answer it
- A mechanic's written opinion linking the fault to how the car was handled
Outside the carrier's control
- What it means
- An act-of-God or inherent-vice argument: weather, debris, or a condition of the car itself
- What can answer it
- Evidence of how the car was secured and stored, plus the carrier's burden of proof
Filed late or filed wrong
- What it means
- The claim missed a contract deadline, or was never a proper written claim
- What can answer it
- The dates you can prove, and the federal minimums a contract cannot undercut
Get the denial, and its reasoning, in writing
Federal rules give the carrier a schedule to keep, and require its decision to reach you in writing. A refusal delivered by phone, or a claim that goes quiet, is not the carrier meeting that obligation.
The rule requires a written decision. It does not require the letter to explain itself, which is why so many denials run to one line. Ask, in writing, for three things together.
- The reason, stated specificallyNot "no carrier liability", but which fact about your shipment leads there.
- The exact language relied onThe contract clause, or the cargo policy exclusion, quoted and identified by section.
- The documents they usedThe copy of the bill of lading the adjuster read, the photos they had, and any inspection report. What the other side is looking at often explains the denial on its own.
The clock is still running
A denial starts a second deadline, and it is the one people miss while they argue. Federal law sets minimums for interstate shipments: a contract may give you more time, never less.
These claim rules apply to the carrier that moved the car, not the broker that arranged the job. If you are being passed back and forth, direct the claim at the carrier and use the broker as pressure.
Act of God, inherent vice, and who has to prove what
Two phrases turn up in denial letters more than any others. An act of God means weather or an event nobody could have prevented. Inherent vice means the damage came from a condition of the vehicle itself rather than anything that happened to it: a leaking seal, rust under a panel, a battery already failing.
These are real defenses. They are also the carrier's to prove, not yours to disprove, and proving one is not the same as asserting it.
That changes the tone of your reply. You are not obliged to show the hailstorm was avoidable. You can ask what the carrier did about the forecast, how the car was secured and where it was parked, and point out that a defense has to be supported. Whether one holds up in your case is a legal question, and the answer turns on facts a lawyer would want to see.
How to escalate, in order
- Answer the stated reasonOne reply, addressing the exact ground given, with the evidence attached. Do not re-argue the whole claim.
- Push the brokerA broker's ongoing relationship with the carriers it dispatches to moves stalled claims more often than your emails will. Ask it to take the claim up directly.
- Go to the carrier's insurerAsk for the certificate of insurance, then deal with the insurer rather than the dispatcher.
- Tell your own insurerIf your policy covers the car in transit, your insurer may pay and pursue the carrier itself. Ask what a claim would do to your policy first.
- File an FMCSA complaintIt will not pay your repair bill, but a carrier that ignores the federal claim schedule belongs on the record.
- Small claims courtMost car shipping damage sits within small claims limits, and you usually need no lawyer. Check your court's limit, fees and rules for suing an out-of-state company.
What good photos actually change
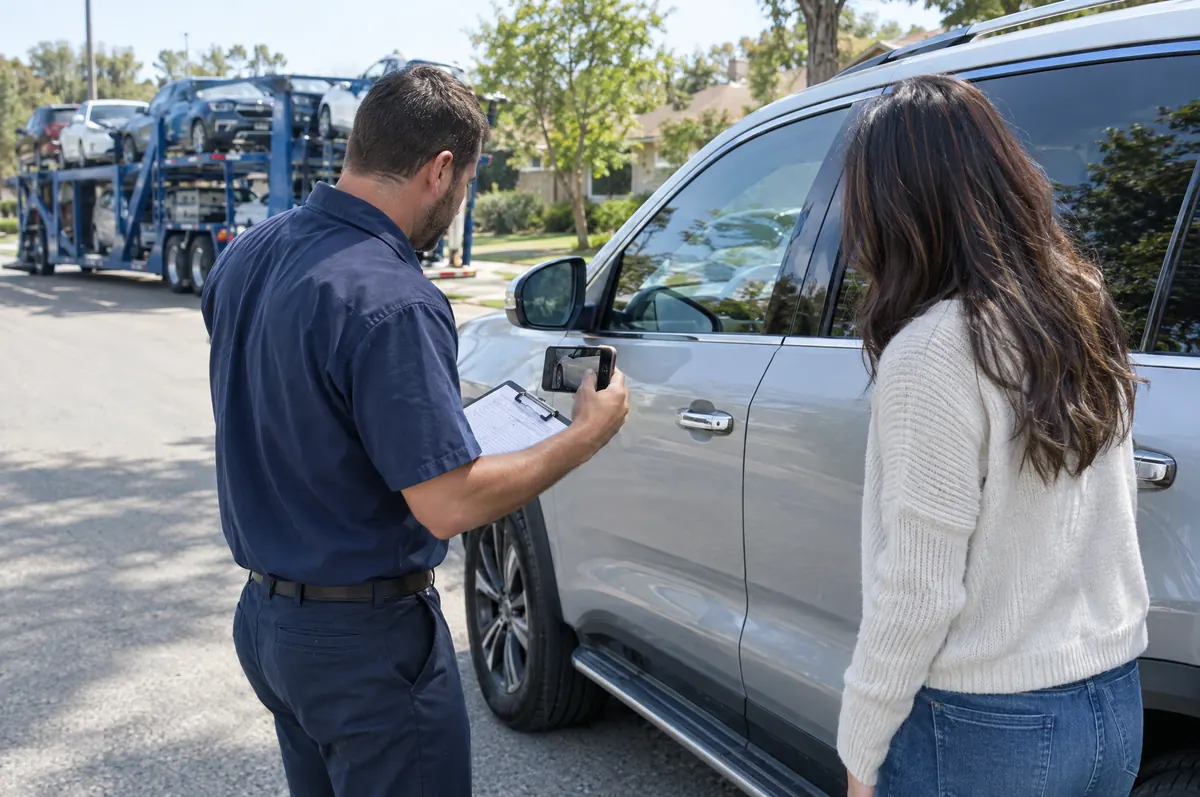
Almost every denial in the table above is really a denial about proof. A claim turns on one question: was the damage there when the carrier took the car? Photographs are the only thing most people have that answers it.
- Shoot the whole car in daylight before pickup: four sides, roof, wheels, glass, bumpers and the odometer.
- Photograph every existing mark close up, and again from far enough back to show where on the car it sits.
- Repeat the same shots in the same order at delivery, before you sign anything.
- Keep the originals with their metadata. A screenshot loses the timestamp that makes the photo useful.
- Get the truck into at least one frame at each end, so the car and the carrier appear together.
The pairing is what persuades an adjuster. One clean photo of a panel at pickup and one of the same panel damaged at delivery, both timestamped, beats pages of description.
When to bring in a lawyer or your own insurer
Most denied claims are worth one careful reply and, if that fails, a small claims filing. Some are not, and it helps to tell which is which early rather than after a year of email.
- The repair estimate is beyond your small claims limit, or the car is a total loss.
- The denial rests on contract wording, a limitation of liability or a released-value term, and you cannot tell whether it is enforceable.
- The carrier has stopped responding and your deadline to sue is approaching.
- You are being asked to sign a release in exchange for a partial payment.
Call your own auto insurer before the lawyer. Ask whether your policy covers the car in transit, what a claim would cost you in deductible and premium, and whether the insurer would pursue the carrier itself. The call is free, and it sometimes ends the problem.
Frequently asked questions
My claim was denied. What is the first thing to do?
Ask in writing for the specific reason, the exact contract or policy language it relies on, and copies of the documents the adjuster used. Most denials run one line, and the reasoning is where the argument is.
How long do I have to sue after a denial?
For interstate shipments, a carrier cannot give you less than 2 years from the date it denies a claim in writing. Your contract may allow longer. Negotiating with the adjuster does not extend it.
I signed the bill of lading before I saw the damage. Is the claim dead?
It is much harder, not dead. Photograph the damage immediately, write to the carrier and broker the same day, and send anything from delivery day that shows the car's condition as it came off the truck.
The bill of lading, explainedThey say it was an act of God. Can they do that?
They can raise it, but the Supreme Court has held that the burden is on the carrier to show both that it was free from negligence and that the damage came from one of the excepted causes.
Can the broker be made to pay?
Usually not for transit damage: the carrier held your car, and the federal claim rules apply to it. A broker is still often the most effective route to a stalled claim, because it decides which carriers it keeps using.
Broker vs. carrierWhat if the carrier just ignores my claim?
Federal rules require a carrier to acknowledge a written claim within 30 days and to pay, decline or make a firm settlement offer in writing within 120 days. Silence breaks that schedule and belongs in an FMCSA complaint.
File a complaint
Sources
- 49 CFR Part 370
- 49 U.S.C. 14706(e)
- Missouri Pacific R. Co. v. Elmore & Stahl, 377 U.S. 134 (1964)
- 49 CFR 387.9
Written and reviewed by the Haulwide editorial team. Editorial policy